It was a tale of 2 markets this week, with AI related equities getting punished and bonds and banks reaping the rewards. Some are describing it as a flight to safety triggered by concerns over rising debt loads amongst the hyperscalers, escalation of conflicts in the Middle East and Ukraine, and higher than expected inflation numbers in the US. The TSX beat the S&P500, bond yields fell, oil rose and the Canadian dollar strengthened slightly.
| Index | Close Oct. 8th 2026 | Close Oct. 15th 2026 |
| S&P500 | 7,771 | 7,742 |
| TSX60 | 35,149 | 36,137 |
| Canada 10 yr. Bond Yield | 3.93% | 3.83% |
| US 10 yr. Treasury Yield | 5.23% | 5.08% |
| USD/CAD | $1.42423 | $1.41894 |
| Brent Crude | $103.38 | $105.75 |
| Gold | $4,136 | $4,170 |
| Bitcoin | $81,693 | $82,083 |
Source: Trading Economics
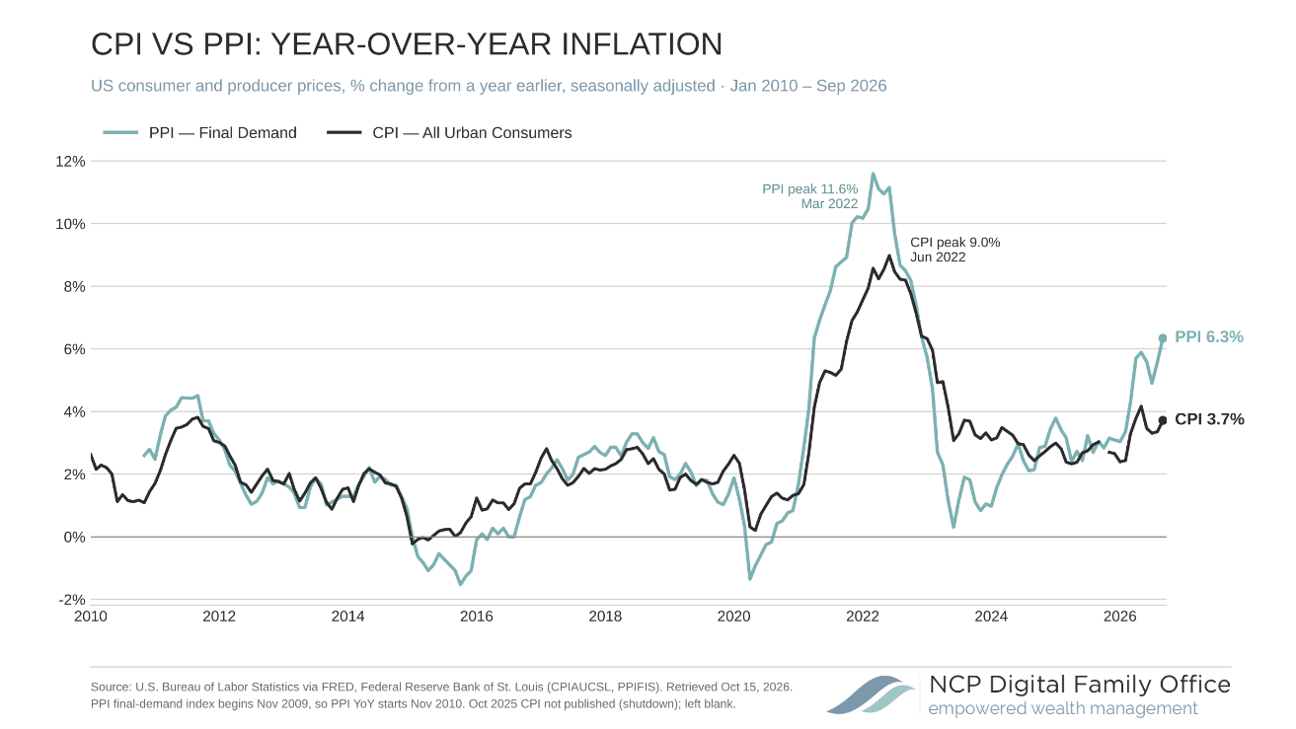
We’ll start with inflation in the US which surprised to the upside at both the consumer (CPI) and wholesale (PPI) levels. September’s headline CPI rose by 3.7% year over year (YoY) which was higher than August’s 3.4% reading. Core CPI which excludes energy and food was up 2.6% YoY up from August’s 2.4% reading. While energy (gas) prices drove most of the headline number, core shows us that inflation is accelerating across a wider range of goods and services.
Compounding the CPI reading was a sharp uptick in the Producer Price Index (PPI) which measures inflation at the wholesale level. A rise here can be expected to show up in the CPI down the road as wholesale price rises get passed on. Headline PPI rose by 6.3% YoY well above August’s reading of 5.6%. Core PPI rose by 5% YoY, its highest reading since January of 2023. Both CPI & PPI are accelerating which will put pressure on the Federal Reserve to raise rate. Markets are not expecting a hike before the mid-term elections but are baking in a December hike.
Despite higher inflation, bond yields retreated. This flight to safety was triggered by concerns over revenue growth and capital need by AI hyperscalers. If this seems a bit manic depressive after the rise in bond yields driven by the demand for capital, I will posit that is a feature not a bug of the bond market.
The combination of higher rates and inflation are putting the squeeze on the US consumer. The share of seriously delinquent auto loans hit a record high while 13% of credit card balances are significantly past due, close to their 2010 peak post the financial crisis. Exacerbating the problem are mortgage rates that have climbed to 7.4% shutting many potential buyers out of the housing market.
Despite tariffs, China’s exports to the world grew by 36.3% in September compared to a year ago. For the first 9 months of the year China recorded a $938 billion trade surplus. This has hit the European Union especially hard where the trade deficit with the China is over $1.1 billion per day. Now a deal has been reached to reduce imports of hybrid EV cars by 50%. Which will be good news to Stellantis which is preparing to launch an all-electric Deux Chevaux (2CV).
This next item is tied to the last. China built its export and manufacturing prowess on providing the world with cheap goods. Consumers voted with their wallets, and we have benefited as individuals with access to inexpensive consumer goods and electronics. China is now replicating that export model into AI technology. As this piece from BCG illustrates the AI strategies of the US and China have diverged. The US has taken the capital-intensive road of developing frontier models and building out AI infrastructure. China has adopted an open-source approach pushing ahead on cost-optimized models and accelerating adoption across its economy. The market for China’s AI stack will not be the west. It will be the global south where China is the #1 trade partner thanks to the cost advantage and products that fit the market.
Canada’s Women’s Rugby Team faces off against England this weekend in Toronto. The game is a rematch after a heartbreaking loss to England in the World Cup Final last year. We’ll dedicate this classic from Queen to the Canadian Women – Allez les Rouge!!
Russ Lazaruk, RIAC, CIWM, CIM, FCSI
Managing Director & Portfolio Manager